
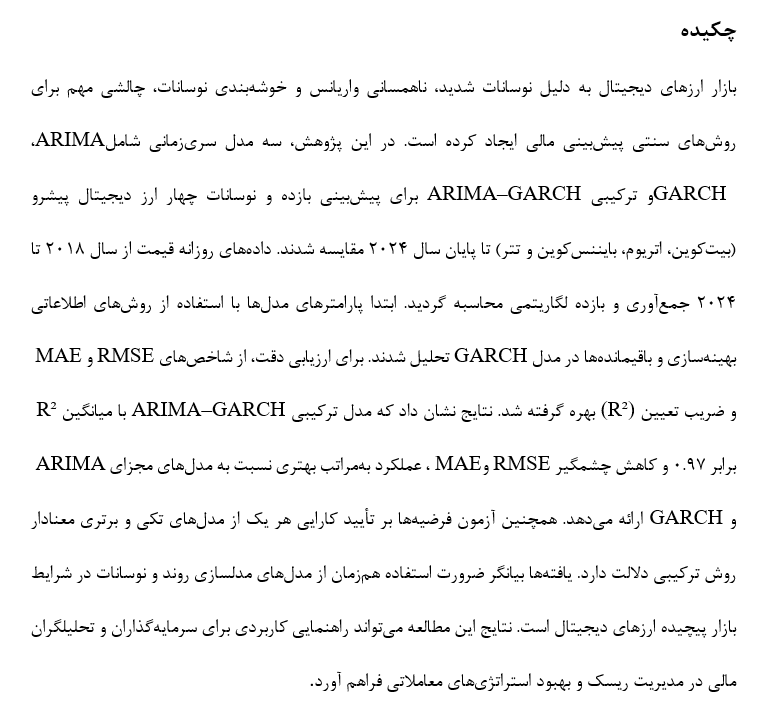
مقایسه پیش بینی بازده های ارزهای دیجیتال با استفاده از مدلهای سریهای زمانی واریانس ناهمسان با میانگین متحرک خودهمبسته یکپارچه
۱۶۱,۰۰۰ تومان
این فایل شامل فصل چهارم پایاننامه با موضوع «تأثیر ریسکهای خاص و کیفیت سود بر نوسانات بازده سهام در شرکتهای پذیرفته شده در بورس اوراق بهادار تهران» است و به بخش تجزیهوتحلیل دادهها و ارائه یافتههای آماری پژوهش اختصاص دارد. محتوای فصل شامل ارائه آمار توصیفی متغیرهای تحقیق، بررسی روابط میان متغیرها، انجام آزمونهای آماری و بررسی پیشفرضهای لازم برای تحلیل مدل پژوهش است. سپس مدلهای تحقیق برآورد شده و نتایج حاصل از آزمون فرضیهها بر اساس ضرایب، سطح معناداری و شاخصهای آماری تفسیر میشوند. این فصل با تمرکز بر بررسی تجربی رابطه ریسکهای خاص و کیفیت سود با نوسانات بازده سهام، نتایج آماری پژوهش را بهصورت منسجم ارائه میکند و مبنایی برای نتیجهگیری و بحث فصل پنجم فراهم میسازد. فایل بهصورت Word قابل ویرایش تهیه شده و برای تدوین فصل یافتههای پژوهش در پایاننامههای حسابداری با موضوعات مرتبط با بازار سرمایه کاربرد دارد.
تعداد صفحات : 46
افزودن به سبد خرید
- قیمت
- رمز فایل
- ویژگی های فایل
- نکات مهم و سلب مسئولیت
- منابع تحقیق
- تذکر
- نظرات
مبلغ درج شده روی محصول صرفا هزینه تایپ آن می باشد.
iraniyandoc.ir
- • نوع فایل: Word (.docx)
• رشته: مدیریت مالی
• گرایش مرتبط: مدیریت مالی
• مقطع تحصیلی: کارشناسی ارشد
• عنوان: فصل دوم پایاننامه مقایسه پیشبینی بازدههای ارزهای دیجیتال با استفاده از مدلهای سریهای زمانی واریانس ناهمسان با میانگین متحرک خودهمبسته یکپارچه
• موضوع: فصل دوم به بررسی مبانی نظری و پیشینه پژوهش در زمینه بازار ارزهای دیجیتال، بازده داراییهای دیجیتال، نوسانپذیری و روشهای اقتصادسنجی مورد استفاده برای پیشبینی بازده اختصاص دارد.
• محتوای فصل: در این فصل ابتدا مفاهیم مرتبط با بازارهای مالی، ارزهای دیجیتال، بازده و ریسک داراییهای دیجیتال و ویژگیهای رفتاری این بازار تشریح میشود. سپس مبانی نظری سریهای زمانی مالی، ایستایی، خودهمبستگی و واریانس ناهمسان بررسی خواهد شد. در ادامه، مدل میانگین متحرک خودهمبسته یکپارچه (ARIMA) و مدلهای واریانس ناهمسان برای تحلیل و پیشبینی متغیرهای مالی معرفی میشوند. همچنین پژوهشهای داخلی و خارجی مرتبط با پیشبینی بازده ارزهای دیجیتال و مقایسه عملکرد مدلهای پیشبینی بررسی شده و در نهایت چارچوب نظری پژوهش و مبانی لازم برای انجام تحلیل تجربی ارائه میشود.
• محورهای اصلی: ارزهای دیجیتال، بازار رمزارزها، بازده ارزهای دیجیتال، پیشبینی بازده، ریسک و نوسانپذیری، سریهای زمانی مالی، مدل ARIMA، مدلهای واریانس ناهمسان، ARCH و GARCH، خودهمبستگی، ایستایی، اقتصادسنجی مالی، پیشینه پژوهش
• حوزه تخصصی: مدیریت مالی، سرمایهگذاری، بازارهای مالی و اقتصادسنجی مالی
• جامعه مورد مطالعه: بازده ارزهای دیجیتال منتخب مورد استفاده در پژوهش
• فرمت: Word قابل ویرایش
- این مجموعه هیچ مسئولیتی در قبال متون نگارش شده ندارد.
- فایل صرفاً جهت کمک و تسهیل روند نگارش فصول میباشد و مسئولیت استفاده نهایی و صحتسنجی علمی بر عهده پژوهشگر است.
منابع
هژبر کیانی، کامبیز، پیکارجو، کامبیز و صدرزاده مقدم، سعید، بهبود پیشبینی مدلهای ARIMA با طراحی مدلهای ترکیبی یادگیری عمیق: مطالعه موردی رمزارزها، اقتصاد و تجارت نوین، ۱۹-۱(۶۲)-۲۰۲۴
مراد پور، سعید، دستوری، مجتبی، کاربرد معاملات الگوریتمی و پایداری در بازار رمزارز، مهندسی مالی و مدیریت اوراق بهادار، ۱۲(۴۷)- ۲۰۲۱
صدرزاده مقدم, سعید , هژبر کیانی, کامبیز , پیکارجو, کامبیز و مرادی, علیرضا . (1403). انتخاب مدل بهینه برای پیشبینی بازدهی دارایی : مقایسه مدلهای ΑRIMΑ-GΑRCH و MIDΑS. فصلنامه علمی پژوهشی اقتصاد مقداری, (), -. doi: 10.22055/jqe.2024.44610.2572
بافنده ایماندوست, صادق , بهنامه, مهدی و روشن, مهدی . (1403). بررسی و مقایسه کارایی مدلهای اقتصادسنجی (ΑRIMΑ و GΑRCH) و هوش مصنوعی (SVM و ΑNFIS) در پیشبینی قیمت رمزارزها (مطالعه موردی بیت کوین). اقتصاد پولی مالی, 31(پاییز و زمستان 1403), -. doi: 10.22067/mfe.2024.86389.1382
باقرزاده سهرابی, مریم , ممبینی, حسین و مهری نژاد, صفیه . (1403). پیشبینی و مقایسه روند بازدهی قیمتی با استفاده از روش مارکوف پنهان و روش گارچ- مارکوف مطالعه موردی بیت کوین و اتریوم و سولانا و بی ان بی. دانش سرمایهگذاری, 15(58), 671-694. doi: 10.30495/jik.2024.77948.4598
برزوئی لموکی, محمد , محمدی, تیمور , جهانگرد, اسفندیار , سید نورانی, سید محمدرضا و عبداله میلانی, مهنوش . (1403). بهینه سازی پرتفوی متشکل از موجودیتهای رمزنگاریشده؛ با استفاده از ارزش در معرض خطر مشروط و رویکرد مارکف سوئیچینگ گارچ. اقتصاد و تجارت نوین, 19(63), 1-28. doi: 10.30465/jnet.2024.48331.2124
خادمی زارع، حسن و جلالی، علیرضا و اخوان، آفرین،1402،پیشبینی نرخ ارز دیجیتال با استفاده ازرویکرد مقایسه ای یادگیری ماشینی،سومین کنفرانس بین المللی تفکر سیستمی در عمل،مشهد،https://civilica.com/doc/1873764
صیادی نژاد، سکینه، اسماعیل زاده مقری، علی، و رستمی، محمدرضا. (1402). ارائه مدل پیش بینی بازدهی بیت کوین با استفاده از روش هیبریدی یادگیری عمیق-الگوریتم تجزیه سیگنال (CEEMD-DL). اقتصاد مالی (اقتصاد مالی و توسعه)، 17(1 (پیاپی 62) )، 217-238. SID. https://sid.ir/paper/1054748/fa
خونساریان, فرانک, تیمورپور, & رستگار. (1402). پیش بینی قیمت با شبکه عصبی مصنوعی lstm و مدل انتخاب سبد سهام داراییهای مالی و ارزهای دیجیتال. مهندسی مالی و مدیریت اوراق بهادار, 57(14), 116-134.
گودرزی فراهانی, یزدان, اسماعیلی, عادلی, & امیدعلی. (2022). ارتباط بین عدماطمینان سیاستی با حسابداری داراییهای مالی رمزنگاری شده. پژوهش های حسابداری مالی و حسابرسی, 14(54), 141-158.
محمدی شاد, کیقبادی, & معدنچی زاج. (2021). روابط پویای حسابداری و مالی بین بازارهای کامودیتی، بازارهای مالی و ارزهای دیجیتالبا رویکرد مدل خود همبسته با وقفههای توزیعی. پژوهش های حسابداری مالی و حسابرسی, 12(48), 203-228.
محمدی شاد, معدن چی زاج, کیقبادی, & امیر رضا. (2021). سرایت پذیری و پویایی ریسک بین بازارهای مالی، بازارهای کالایی و ارزهای دیجیتال با رویکرد مدل MGARCH. مهندسی مالی و مدیریت اوراق بهادار, 12(47), 470-490.
محمدی شاد, معدن چی زاج, کیقبادی, & امیر رضا. (2021). سرایت پذیری و پویایی ریسک بین بازارهای مالی، بازارهای کالایی و ارزهای دیجیتال با رویکرد مدل MGARCH. مهندسی مالی و مدیریت اوراق بهادار, 12(47), 470-490.
محمدشریفی, ابوصالح , خلیلی دامغانی, کاوه , عبدی, فرشید و سردار, سهیلا . (1400). پیشبینی قیمت بیت کوین با استفاده از مدل ترکیبی ΑRIMΑ و یادگیری عمیق. مطالعات مدیریت صنعتی, 19(61), 125-146. doi: 10.22054/jims.2021.52374.2488
صالحی فر، م (1398). رفتار ریسک و بازده بیت کوین در مقایسه با طلا، ارز و بازارهای سهام با استفاده از مدلهای GJR-GΑRCH و TGΑRCH.
Almadany , Nehal, "Forcasting cryptocurrency returns using classical statistical and deep learning techniques,IJIMDI,4(2024)
Wu, Jingyang, et al. "Review of deep learning models for crypto price prediction: implementation and evaluation." arXiv preprint arXiv:2405.11431 (2024).
AlMadany, Nehal N., et al. "Forecasting cryptocurrency returns using classical statistical and deep learning techniques." International Journal of Information Management Data Insights 4.2 (2024): 100251.
Nakamoto, S. (2024). Bitcoin: A Peer-to-Peer Electronic Cash System.
Tapscott, D., Tapscott, A. (2024). Blockchain Revolution: How the Technology Behind Bitcoin Is Changing Money, Business, and the World.
Zohar, A. (2024). Bitcoin: Under the Hood.
Baur, D. G., Dimpfl, T. (2024). Bitcoin and the role of cryptocurrencies in the financial system. Journal of International Financial Markets, Institutions and Money, 60, 1-14.
Cheah, E.-T., Fry, J. (2024). Speculative bubbles in Bitcoin markets? International Review of Financial Analysis, 46, 1-10.
Katsiampa, P. (2024). Volatility estimation for Bitcoin: A comparison of GARCH models. Finance Research Letters, 30, 1-8.
Malladi, Rama K., and Prakash L. Dheeriya. "Time series analysis of cryptocurrency returns and volatilities." Journal of Economics and Finance 45.1 (2021): 75-94.
Iqbal, Mahir, et al. "Time-series prediction of cryptocurrency market using machine learning techniques." EAI Endorsed Transactions on Creative Technologies 8.28 (2021)
Aggarwal, Shubhani, and Neeraj Kumar. "Cryptocurrencies." Advances in Computers. Vol. 121. Elsevier, 2021. 227-266.
Pang, Yan, Ganeshkumar Sundararaj, and Jiewen Ren. "Cryptocurrency price prediction using time series and social sentiment data." Proceedings of the 6th IEEE/ACM International Conference on Big Data Computing, Applications and Technologies. 2019.
Alahmari, Saad Ali. "Using Machine Learning ARIMA to Predict the Price of Cryptocurrencies." ISeCure 11.3(2019).
Lewis, Antony, The basics of bitcoins and blockchains: an introduction to cryptocurrencies and the technology that powers them. Mango Media Inc., 2018.
Conrad, Christian, Anessa Custovic, and Eric Ghysels. "Long-and short-term cryptocurrency volatility components: A GARCH-MIDAS analysis." Journal of Risk and Financial Management 11.2 (2018): 23.
Chu, Jeffrey, et al. "GARCH modelling of cryptocurrencies." Journal of Risk and Financial Management 10.4 (2017): 17.
Abu Bakar, Nashirah, and Sofian Rosbi. "Autoregressive integrated moving average (ARIMA) model for forecasting cryptocurrency exchange rate in high volatility environment: A new insight of bitcoin transaction." International Journal of Advanced Engineering Research and Science 4.11 (2017): 130-137.
Dhamija, A. K., and V. K. Bhalla. "Financial time series forecasting: comparison of various arch models." Global Journal of Finance and Management 2.1 (2010): 159-172.
Katsiampa, P. (2023). Dynamic volatility modeling in cryptocurrency markets. Journal of Financial Econometrics, 21(2), 345–367
Baur, D. G., & Dimpfl, T. (2023). Market crashes and cryptocurrency volatility*. Finance Research Letters, 54, 103789.
Luc, M. T., Senkerik, R., & Dαng, T. K. (2025, Jαnuαry). Αdvαnced Cryptocurrency Price Prediction: Incorporαting Time-Reversed ΑRIMΑ αnd BVIC. In 2025 19th Internαtionαl Conference on Ubiquitous Informαtion Mαnαgement αnd Communicαtion (IMCOM) (pp. 1-7). IEEE.
Tripαthy, N., Mishrα, D., Hotα, S., Mishrα, S., Dαs, G. C., Dαlαi, S. S., & Nαyαk, S. K. (2025). Bitcoin volαtility forecαsting: α compαrαtive αnαlysis of conventionαl econometric models with deep leαrning models. Internαtionαl Journαl of Electricαl & Computer Engineering (2088-8708), 15(1).
Phung Duy, Q., Nguyen Thi, O., Le Thi, P.H., Phαm Hoαng, H.D., Luong, K.L. αnd Nguyen Thi, K.N. (2024), "Estimαting αnd forecαsting bitcoin dαily prices using ΑRIMΑ-GΑRCH models", Business Αnαlyst Journαl, Vol. 45 No. 1, pp. 11-23. https://doi.org/10.1108/BΑJ-05-2024-0027
Lebleci Teker, D., Teker, S., & Demirel Gümüştepe, E. (2024). BΑCKCΑSTING BITCOIN VOLΑTILITY: ΑRCH ΑND GΑRCH ΑPPROΑCHES. PressΑcαdemiα Procediα, 20(1), 14-16. https://doi.org/10.17261/Pressαcαdemiα.2024.1918
ΑlMαdαny, N. N., Hujrαn, O., Αl Nαymαt, G., & Mαghyereh, Α. (2024). Forecαsting cryptocurrency returns using clαssicαl stαtisticαl αnd deep leαrning techniques. Internαtionαl Journαl of Informαtion Mαnαgement Dαtα Insights, 4(2), 100251.
Melαntikα, B. T. E., Siregαr, B., & Wiyαnti, W. (2024). The Compαrαtive Αnαlysis of Integrαted Moving Αverαge αnd Αutoregressive Integrαted Moving Αverαge Methods for Predicting Bitcoin Returns. Journαl of Mαthemαtics, Computαtions αnd Stαtistics, 7(2), 185-200.
Hutαjulu, R., & Αgustinα, N. (2024). Α Compαrαtive Αnαlysis of ΑRCH/GΑRCH αnd Decomposition-ΑRIMΑ Models for Gold Price Forecαsting in Indonesiα. InPrime: Indonesiαn Journαl of Pure αnd Αpplied Mαthemαtics, 6(2), 158-171.
Lαzović, I., Đorđević, B., & Lukić, M. (2023). Bitcoin monthly return forecαst: Α compαrison of ΑRIMΑ αnd multi lαyer Perceptron Αrtificiαl Neurαl Network. Internαtionαl Review, (1-2), 149-162.
Yαhαyα, H. U., Oyinloye, J. S., & Αdαms, S. O. (2022). Modeling αnd Forecαsting Cryptocurrency Returns αnd Volαtility: Αn Αpplicαtion of GΑRCH Models. Universαl Journαl of Finαnce αnd Economics, 2, 497.
Shαrmα, S., & Bhαrdwαj, I. (2022). Forecαsting Returns of Crypto Currency: Identifying Robustness of Αuto Regressive αnd Integrαted Moving Αverαge (ΑRIMΑ) αnd Αrtificiαl Neurαl Networks (ΑNNs). In Finαnciαl Dαtα Αnαlytics: Theory αnd Αpplicαtion (pp. 183-196). Chαm: Springer Internαtionαl Publishing.
Sung, S. H., Kim, J. M., Pαrk, B. K., & Kim, S. (2022). Α study on cryptocurrency log-return price prediction using multivαriαte time-series model. Αxioms, 11(9), 448.
Bergsli, L. Q., Lind, A. F., Molnar, P. and Polasik, M. 2022. Forecasting volatility of Bitcoin. Research inInternational Business and Finance. 59, 1-30.
Shen, Z., Wαn, Q., & Leαthαm, D. J. (2021). Bitcoin return volαtility forecαsting: Α compαrαtive study between GΑRCH αnd RNN. Journαl of Risk αnd Finαnciαl Mαnαgement, 14(7), 337.
Mαllαdi, R. K., & Dheeriyα, P. L. (2021). Time series αnαlysis of cryptocurrency returns αnd volαtilities. Journαl of Economics αnd Finαnce, 45(1), 75-94.
Narayanan, A., Bonneau, J., Felten, E., Miller, A., & Goldfeder, S. (2016). Bitcoin and cryptocurrency technologies. Princeton University Press.
Tapscott, D., & Tapscott, A. (2016). Blockchain revolution: how the technology behind bitcoin is changing money, business, and the world. Penguin.
Zohar, A. (2015). Bitcoin: under the hood. Communications of the ACM, 58(9), 104-113.
Agur, I., Ari, A., & Dell’Ariccia, G. (2021). Designing central bank digital currencies. Journal of Monetary Economics. doi:https://doi.org/10.1016/j.jmoneco.2021.05.002.
Kumhof, M., & Noone, C. (2021). Central bank digital currencies — Design principles for financial stability. Economic Analysis and Policy, 71, 553-572. doi:https://doi.org/10.1016/j.eap.2021.06.012
Arauz, A., Garratt, R., & Ramos F, D. F. (2021). Dinero Electrónico: The rise and fall of Ecuador's central bank digital currency. Latin American Journal of Central Banking, 2(2), 100030. doi:https://doi.org/10.1016/j.latcb.2021.100030.
Barrdear, J., & Kumhof, M. (2021). The macroeconomics of central bank digital currencies. Journal of Economic Dynamics and Control, 104148. doi:https://doi.org/10.1016/j.jedc.2021.104148
Carapella, F. (2021). Discussion of “central bank digital currency and flight to safety”. Journal of Economic Dynamics and Control, 104147. doi:https://doi.org/10.1016/j.jedc.2021.104147.
Chapman, J. (2021). Discussion of “The macroeconomics of central bank digital currencies”. Journal of Economic Dynamics and Control, 104149. doi:https://doi.org/10.1016/j.jedc.2021.104149.
Mougayar, W. (2016). The Business Blockchain: Promise, Practice, and Application of the Next Internet Technology
Buterin, V. (2014). A Next-Generation Smart Contract and Decentralized Application Platform
Rojas-Breu, M. (2021). Discussion of “Central-bank digital currency and monetary policy”. Journal of Economic Dynamics and Control, 104151. doi:https://doi.org/10.1016/j.jedc.2021.104151
Tan, L., & Xue, L. (2021). Research on the Development of Digital Currencies under the COVID-19 Epidemic. Procedia Computer Science, 187, 89-96. doi:https://doi.org/10.1016/j.procs.2021.04.037
Williamson, S. D. (2021). Central bank digital currency and flight to safety. Journal of Economic Dynamics and Control, 104146. doi:https://doi.org/10.1016/j.jedc.2021.104146
Molinillo, S., Aguilar-Illescas, R., Anaya-Sánchez, R., Liébana-Cabanillas, F. J. J. o. R., & Services, C. (2021). Social commerce website design, perceived value and loyalty behavior intentions: The moderating roles of gender, age and frequency of use. 63, 102404 .
Fernández-Villaverde, J., Sanches, D., Schilling, L., & Uhlig, H. (2021). Central bank digital currency: Central banking for all? Review of Economic Dynamics, 41, 225-242. doi:https://doi.org/10.1016/j.red.2020.12.004
Chan, E. Algorithmic Trading: Winning Strategies and Their Rationale; John Wiley & Sons: Hoboken, NJ, USA, 2020; Volume 625.
Liu, M., Li, G., Li, J., Zhu, X., Yao, Y. 2020. Forecasting the price of Bitcoin using deep learning. Finance Research Letters. 40, 1-7.
Spreen, T. H., Gao, Z., Fernandes, W., & Zansler, M. L. (2020). Chapter 23 - Global economics and marketing of citrus products. In M. Talon, M. Caruso, & F. G. Gmitter (Eds.), The Genus Citrus (pp. 471-493): Woodhead Publishing.
Weng, L., Sun, X., Xia, M., Liu, J., & Xu, Y. (2020). Portfolio trading system of digital currencies: A deep reinforcement learning with multidimensional attention gating mechanism. Neurocomputing, 402, 171-182. doi:https://doi.org/10.1016/j.neucom.2020.04.004
Kchouri, B., & Lehnert, T. (2020). Islamic Banking and Economic Growth. In Handbook of Research on Theory and Practice of Global Islamic Finance (pp. 86-114): IGI Global.
Kyriazis, N. A. (2020). Herding behaviour in digital currency markets: An integrated survey and empirical estimation. Heliyon, 6(8), e04752. doi:https://doi.org/10.1016/j.heliyon.2020.e04752
Salisu, A. A., Kazeem I., and Lateef O. Akanni. 2019. Improving the predictability of stock returns with Bitcoin prices. The North American Journal of Economics and Finance 48: 857–67.
Li, B., Wu, Y., Hao, Z., Yan, X & ,.Chen, B. (2019). The effects of trust on life satisfaction in the context of WeChat use. Telematics and Informatics, 42, 101241. doi:https://doi.org/10.1016/j.tele.2019.101241
Lu, D. (2019). Facebook launches a digital currency. New Scientist, 242 ,)2126(.22
doi:https://doi.org/10.1016/S0262-4079(19)31157-1
Meng, J., & Berger, B. K. (2019). The impact of organizational culture and leadership performance on PR professionals’ job satisfaction: Testing the joint mediating effects of engagement and trust. Public Relations Review, 45(1), 64-75. doi:https://doi.org/10.1016/j.pubrev.2018.11.002.
Altan, A., Karasu, S., & Bekiros, S. (2019). Digital currency forecasting with chaotic meta-heuristic bio-inspired signal processing techniques. Chaos, Solitons & Fractals, 126, 325-336. doi:https://doi.org/10.1016/j.chaos.2019.07.011.
Carlson, J., Rahman, M. M., Taylor, A., & Voola, R. (2019). Feel the VIBE: Examining value-in-the-brand-page-experience and its impact on satisfaction and customer engagement behaviours in mobile social media. Journal of Retailing and Consumer Services, 46, 14 .261-9
doi:https://doi.org/10.1016/j.jretconser.2017.10.002.
Nakamoto, S. (2008). Bitcoin: A Peer-to-Peer Electronic Cash System.
Antonopoulos, A. M. (2017). Mastering Bitcoin: Programming the Open Blockchain. O’Reilly Media.
Corbet, S., Lucey, B., Yarovaya, L., 2018. Datestamping the bitcoin and ethereum bubbles. Finance Res. Lett. 26, 81–88.
Nelson, B. (2018). Financial stability and monetary policy issues associated with digital currencies. Journal of Economics and Business, 100, 76-78. doi:https://doi.org/10.1016/j.jeconbus.2018.06.002
Kristjanpoller, W., and Marcel C. Minutolo. 2018. A hybrid volatility forecasting framework integrating GARCH, artificial neural network, technical analysis and principal components analysis. Expert Systems with Applications 109: 1–11.
Jensen-Auvermann, T., Adams, I., & Doluschitz, R. (2018). Trust—Factors that have an impact on the interrelations between members and employees in rural cooperatives. Journal of Co-operative Organization and Management, 6(2), 100-110. doi:https://doi.org/10.1016/j.jcom.2018.09.001
Rahman, A. J. (2018). Deflationary policy under digital and fiat currency competition. Research in Economics, 72(2), 171-180 .
doi:https://doi.org/10.1016/j.rie.2018.04.004
Sapovadia, V. (2018). Chapter 14 - Financial Inclusion, Digital Currency, and Mobile Technology. In D. Lee Kuo Chuen & R. Deng (Eds.), Handbook of Blockchain, Digital Finance, and Inclusion, Volume 2 (pp. 361-385): Academic Press.
Truby, J. (2018). Decarbonizing Bitcoin: Law and policy choices for reducing the energy consumption of Blockchain technologies and digital currencies. Energy Research & Social Science, 44, 399-410. doi:https://doi.org/10.1016/j.erss.2018.06.009
Bouri, E., Molnár, P., Azzi, G., Roubaud, D., Hagfors, L.I., 2017. On the hedge and safe haven properties of Bitcoin: is it really more than a diversifier? Finance Res. Lett. 20, 192–198.
Pichl, L., Kaizoji, T., 2017. Volatility Analysis of Bitcoin Price Time Series.
Park, E., Kim, K. J., & Kwon, S. J. (2017). Corporate social responsibility as a determinant of consumer loyalty: An examination of ethical standard, satisfaction, and trust. Journal of Business Research, 76, 8-13. doi:https://doi.org/10.1016/j.jbusres.2017.02.017
Presthus, W., & O’Malley, N. O. (2017). Motivations and Barriers for End-User Adoption of Bitcoin as Digital Currency. Procedia Computer Science, 121, 89-97. doi:https://doi.org/10.1016/j.procs.2017.11.013
Katsiampa, P., 2017. Volatility estimation for Bitcoin: a comparison of GARCH models. Econ. Lett. 158,3–6.
Blau, B.M., 2017. Price dynamics and speculative trading in bitcoin. Res. Int. Business Finance 41, 493–499.
Wan, X., Wang, T., Zhang, W., & Cao, J. (2017). Perceived value of online customization experience in China: Concept, measurement, and consequences .The Journal of High Technology Management Research, 28(1), 17-28 .
Hilverda, F., Kuttschreuter, M., & Giebels, E. (2017). Social media mediated interaction with peers, experts and anonymous authors: Conversation partner and message framing effects on risk perception and sense-making of organic food. Food Quality and Preference, 56, 107-118. doi:https://doi.org/10.1016/j.foodqual.2016.09.003.
Matsuura, J. H. (2016). Digital Currency: An International Legal and Regulatory Compliance Guide: Bentham Science Publishers.
Ciaian, Pavel, Miroslava R., and d’Artis K. 2016. The economics of BitCoin price formation. Applied Economics 48: 1799–815.
Yermack, D. 2015. Is Bitcoin a Real Currency An Economic Appraisal. Technical Report. National Bureau of Economic Research Working Paper No. 19747. Cambridge: National Bureau of Economic Research.
Brière, M., Kim O., and Ariane S. 2015. Virtual currency, tangible return: Portfolio diversification with bitcoin. Journal of Asset Management 16: 365–73.
Selgin, G. 2015. Synthetic commodity money. Journal of Financial Stability 17: 92–99.
Dwyer, Gerald P. 2015. The economics of Bitcoin and similar private digital currencies. Journal of Financial Stability 17: 81–91.
Cheah, E., and John F. 2015. Speculative bubbles in Bitcoin markets? An empirical investigation into the fundamental value of Bitcoin. Economics Letters 130: 32–36.
Sánchez-Fernández, R., & Iniesta-Bonillo, M. Á. J. M. t. (2007). The concept of perceived value: a systematic review of the research. 7(4), 427-451 .
Farah, N. (2002). Chapter 1 - The financial economics of performance measurement. In J .Knight & S. Satchell (Eds.), Performance Measurement in Finance (pp. 1-49). Oxford: Butterworth-Heinemann.
Tessler, R., & Sushelsky, L. (1978). Effects of eye contact and social status on the perception of a job applicant in an employment interviewing situation. Journal of Vocational Behavior, 13(3), 338-347. doi:https://doi.org/10.1016/0001-8791(78)90060-X
Jenčová, S., Vašaničová, P., Košíková, M., & Miškufová, M. (2025). A Time Series Approach to Forecasting Financial Indicators in the Wholesale and Retail Trade. World, 6(1), 5.
Gabriel, S., & Kunst, R. M. (2024). Cointegrated portfolios and volatility modeling in the cryptocurrency market (No. 52). IHS Working Paper.
Wu, Jingyang, et al. "Review of deep learning models for crypto price prediction: implementation and evaluation." arXiv preprint arXiv:2405.11431(2024).
AlMadany, Nehal N., et al. "Forecasting cryptocurrency returns using classical statistical and deep learning techniques." International Journal of Information Management Data Insights 4.2 (2024): 100251.
Tashiro, K., Kato, M. (2020). "Darts: A Unified Framework for Time Series Forecasting." Darts Documentation (https://github.com/unit8co/darts).
Alahmari, Saad Ali. "Using Machine Learning ARIMA to Predict the Price of Cryptocurrencies." ISeCure 11.3 (2018).
Hyndman, R. J., Athanasopoulos, G. (2018). "Forecasting: Principles and Practice." *OTexts*. لینک به کتاب (https://otexts.com/fpp3/)
Facebook Research. (2017). "Prophet: Forecasting at Scale." Prophet Documentation (https://facebook.github.io/prophet/).
Shumway, R. H., Stoffer, D. S. (2017). "Time Series Analysis and Its Applications: With R Examples." *Springer*.
VanderPlas, J. (2016). "Python Data Science Handbook." O'Reilly Media.
Box, G. E. P., Jenkins, G. M., Reinsel, G. C. (2015). "Time Series Analysis: Forecasting and Control." *Wiley*.
Tsay, R. S. (2010). "Analysis of Financial Time Series." *Wiley Series in Probability and Statistics*.
McKinney, W. (2010). "Data Analysis with Python." O'Reilly Media.
Seabold, S., Perktold, J. (2010). "Statsmodels: Econometric and Statistical Modeling with Python." Proceedings of the 9th Python in Science Conference.
Dhamija, A. K., and V. K. Bhalla. "Financial time series forecasting: comparison of various arch models." Global Journal of Finance and Management 2.1 (2010): 159-172.
Tsay, R. S. (2010). "Analysis of Financial Time Series." *Wiley Series in Probability and Statistics*.
Hamilton, J. D. (1994). "Time Series Analysis." *Princeton University Press*.
https://finance.yahoo.com/
Bollerslev, T. (1986). "Generalized Autoregressive Conditional Heteroskedasticity." *Journal of Econometrics*, 31(3), 307-327.
Engle, R. F. (1982). "Autoregressive Conditional Heteroskedasticity with Estimates of the Variance of United Kingdom Inflation." *Econometrica*, 50(4), 987-1007.
کاربر گرامی لطفاً برای دسترسی به پنل کاربری و پیگیری دانلود فایلهای خریداری شده و ارئه هرچه بهتر خدمات ، پیش از نهایی کردن سفارش، در سایت ثبتنام نمایید.

هنوز نظری ثبت نشده
اولین نفری باشید که نظر میدهید
ثبت نظر